
Buying Your Dream Home first home is one of the biggest milestones in life. While the process can feel exciting, it can also seem overwhelming with so many decisions to make. From understanding your budget to choosing the right mortgage and finding the perfect property, every step matters. This first-time homebuyer’s guide will help you navigate the journey with confidence and make informed decisions that lead you to your dream home.
Understand Your Budget
Before browsing listings, determine how much home you can realistically afford. Look at your monthly income, existing debts, savings, and future financial goals. Remember that owning a home involves more than just a mortgage payment.
You should also budget for:
- Property taxes
- Homeowners insurance
- Maintenance and repairs
- Utilities
- HOA fees (if applicable)
- Closing costs
Creating a realistic budget helps prevent financial stress after purchasing your home.
Improve Your Credit Score
Your credit score plays a major role in qualifying for a mortgage and securing a competitive interest rate. A higher score can save thousands of dollars over the life of your loan.
To improve your credit:
- Pay bills on time.
- Reduce outstanding debt.
- Avoid opening unnecessary credit accounts.
- Review your credit report for errors.
- Keep credit card balances low.
Lenders typically reward borrowers with strong credit by offering lower mortgage rates.
Save for a Down Payment
Many first-time buyers believe they need a 20% down payment, but that’s not always true. Several loan programs allow much lower down payments depending on your financial situation.
Besides the down payment, you’ll also need savings for:
- Closing costs
- Moving expenses
- Home inspections
- Emergency repairs
- Furniture and appliances
Having additional savings provides peace of mind after moving into your new home.
Get Pre-Approved for a Mortgage
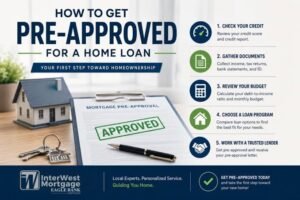
Mortgage pre-approval is one of the smartest first steps before house hunting. During pre-approval, a lender reviews your financial information and determines how much they’re willing to lend.
Benefits include:
- Knowing your price range
- Strengthening your offer
- Showing sellers you’re a serious buyer
- Speeding up the buying process
A pre-approval letter gives you confidence while shopping for homes.
Choose the Right Mortgage
There are several mortgage options available for first-time buyers. Understanding the differences can help you select the best loan for your financial goals.
Common mortgage types include:
- Fixed-rate mortgages
- Adjustable-rate mortgages (ARM)
- FHA loans
- VA loans (for eligible veterans)
- USDA loans (for eligible rural properties)
- Conventional loans
Compare interest rates, loan terms, monthly payments, and lender fees before making your decision.
Find the Right Real Estate Agent
A knowledgeable real estate agent can make the buying process much easier. They understand local market conditions, negotiate on your behalf, and guide you through contracts and paperwork.
Look for an agent who:
- Has experience with first-time buyers
- Knows your desired neighborhood
- Communicates clearly
- Has positive client reviews
- Understands your budget and needs
The right professional can save both time and money.
Start House Hunting
Once you’re pre-approved, it’s time to search for your dream home. Create a list of must-have features and separate them from features you’d simply like to have.
Consider factors such as:
- Neighborhood safety
- School districts
- Commute time
- Nearby shopping and healthcare
- Future property value
- Size and layout
Avoid letting emotions drive your decision. Focus on finding a home that meets your long-term needs.
Schedule a Home Inspection
Never skip a professional home inspection. Even beautiful homes may have hidden issues that could become expensive later.
An inspection typically evaluates:
- Roof condition
- Plumbing
- Electrical systems
- HVAC system
- Foundation
- Structural integrity
Inspection results may allow you to negotiate repairs or a lower purchase price before closing.
Understand Closing Costs
Many first-time buyers overlook closing costs when planning their budget. These expenses usually range between 2% and 5% of the home’s purchase price.
Closing costs may include:
- Loan origination fees
- Appraisal fees
- Title insurance
- Attorney fees
- Recording fees
- Property taxes
Ask your lender for a Loan Estimate early in the process so you understand all expected expenses.
Make an Offer and Close the Deal
Once you’ve found the perfect home, your real estate agent will help prepare a competitive offer. Depending on market conditions, negotiations may include the purchase price, repairs, appliances, or closing costs.
After your offer is accepted:
- Finalize your mortgage.
- Complete the home inspection.
- Obtain homeowners insurance.
- Review closing documents.
- Attend the closing meeting.
- Receive your keys.
Congratulations—you are now a homeowner!
Tips for First-Time Homebuyers
Buying your first home becomes much easier when you plan ahead and stay informed.
Keep these tips in mind:
- Stick to your budget.
- Don’t rush your decision.
- Compare multiple mortgage lenders.
- Maintain stable employment during the mortgage process.
- Avoid taking on new debt before closing.
- Keep emergency savings after purchasing your home.
Patience and preparation are the keys to a successful home purchase.
Final Thoughts
Buying your first home is both exciting and rewarding. While the process may seem complex at first, careful planning, smart budgeting, and professional guidance can make the experience much smoother. By understanding your finances, choosing the right mortgage, working with experienced professionals, and carefully evaluating each property, you’ll be well prepared to purchase a home that fits both your lifestyle and your budget.
Your dream home is more than just a place to live—it’s an investment in your future. Take your time, ask questions, and make informed decisions every step of the way.
Frequently Asked Questions (FAQs)
1. What credit score do first-time homebuyers need?
Most lenders prefer a credit score of 620 or higher, although some government-backed loans may accept lower scores.
2. How much should I save before buying my first home?
Besides your down payment, it’s recommended to save enough for closing costs, moving expenses, and at least three to six months of emergency savings.
3. Is mortgage pre-approval necessary?
Yes. Pre-approval helps determine your budget and shows sellers you’re a serious buyer.
4. What is included in closing costs?
Closing costs typically include lender fees, appraisal fees, title insurance, taxes, attorney fees, and recording charges.
5. Should I get a home inspection?
Absolutely. A professional inspection helps identify hidden issues before you finalize the purchase.