
Buying your dream home is an exciting milestone, but getting approved for a mortgage can sometimes feel like a lengthy and stressful process. Fortunately, there are several steps you can take to Get Approved for Your Dream Home Mortgage Faster your chances of fast approval while securing the best possible loan terms. By preparing your finances, organizing your documents, and understanding what lenders look for, you can move through the mortgage approval process with confidence.
Understand What Mortgage Lenders Look For
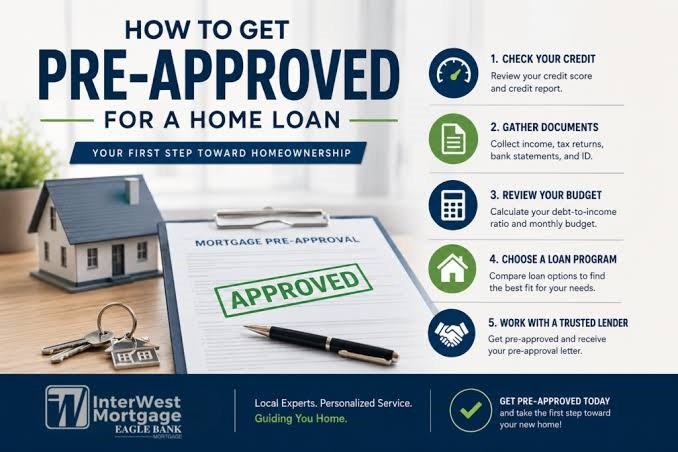
Before approving a mortgage, lenders evaluate your financial health to determine whether you’re able to repay the loan. They typically review:
- Credit score
- Income stability
- Employment history
- Debt-to-income (DTI) ratio
- Down payment amount
- Savings and assets
Strengthening these areas before applying can significantly improve your approval chances.
Improve Your Credit Score
Your credit score is one of the most important factors in mortgage approval. A higher score not only increases your chances of approval but may also qualify you for lower interest rates.
Ways to improve your credit score include:
- Pay all bills on time.
- Reduce credit card balances.
- Avoid opening new credit accounts.
- Check your credit report for errors.
- Keep your credit utilization below 30%.
Even a modest increase in your credit score can lead to better loan offers.
Save for a Larger Down Payment
While many loan programs allow low down payments, saving more money upfront can make lenders view you as a lower-risk borrower.
Benefits of a larger down payment include:
- Higher approval odds
- Lower monthly mortgage payments
- Reduced interest costs
- Less need for private mortgage insurance (PMI)
The more equity you have from the beginning, the stronger your mortgage application becomes.
Lower Your Debt-to-Income Ratio
Your debt-to-income ratio compares your monthly debt payments to your gross monthly income. Most lenders prefer a DTI below 43%, although lower is usually better.
To improve your DTI:
- Pay off credit card balances.
- Eliminate personal loans.
- Avoid financing new vehicles.
- Increase your monthly income if possible.
Reducing debt before applying can greatly improve your mortgage approval chances.
Get Pre-Approved Before House Hunting
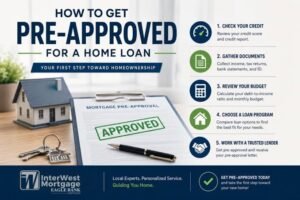
Mortgage pre-approval gives you a clear understanding of your borrowing power. During pre-approval, the lender reviews your finances and issues a letter stating how much you’re qualified to borrow.
Benefits include:
- Faster final approval
- Stronger offers when buying a home
- Better understanding of your budget
- Increased confidence during negotiations
Many sellers prefer buyers who already have a pre-approval letter.
Organize Your Financial Documents
One of the biggest causes of mortgage delays is missing paperwork. Prepare all required documents before submitting your application.
Common documents include:
- Government-issued ID
- Recent pay stubs
- W-2s or tax returns
- Bank statements
- Employment verification
- Investment account statements
Having everything ready allows lenders to process your application more quickly.
Maintain Stable Employment
Mortgage lenders value consistent employment and reliable income. If possible, avoid changing jobs while your mortgage application is under review.
Changing employers or careers during the approval process may require additional verification and delay closing.
Avoid Major Financial Changes
After applying for a mortgage, keep your financial situation as stable as possible.
Avoid:
- Buying a new car
- Opening new credit cards
- Making large purchases
- Missing bill payments
- Closing existing credit accounts
These actions can affect your credit score and debt-to-income ratio, potentially delaying approval.
Work With the Right Mortgage Lender
Not all lenders offer the same processing times or loan options. Compare multiple lenders before making your decision.
Consider:
- Interest rates
- Loan fees
- Customer reviews
- Approval timelines
- Available mortgage programs
Choosing an experienced lender with efficient underwriting can speed up the process significantly.
Respond Quickly to Lender Requests
During underwriting, your lender may request additional documentation or clarification.
Respond promptly by:
- Uploading requested documents immediately.
- Checking emails daily.
- Keeping your phone available.
- Answering questions accurately.
Fast responses help prevent unnecessary delays.
Consider Government-Backed Loan Programs
If you qualify, government-backed mortgages may provide flexible approval requirements.
Popular options include:
- FHA Loans
- VA Loans
- USDA Loans
These programs often help first-time buyers or borrowers with limited savings qualify more easily.
Keep Enough Cash in Reserve
Lenders like to see that borrowers have emergency savings after purchasing a home.
Having reserve funds demonstrates financial stability and may improve your approval chances.
Avoid Common Mortgage Application Mistakes
Many applications are delayed because of avoidable errors.
Common mistakes include:
- Providing inaccurate information
- Forgetting required documents
- Applying for multiple new loans
- Ignoring credit report issues
- Overestimating income
Double-check every detail before submitting your application.
Final Thoughts
Getting approved for your dream home mortgage faster starts with preparation. Improving your credit score, reducing debt, saving for a larger down payment, organizing your financial documents, and getting pre-approved can make the entire process smoother and quicker. Staying financially stable during underwriting and working with a trusted lender further increases your chances of fast approval.
By taking these proactive steps, you’ll be in a stronger position to secure the financing you need and move into your dream home sooner.