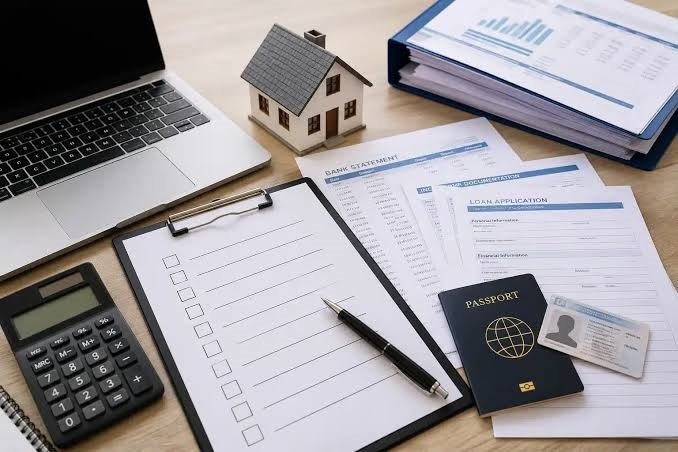

Buying a home is an exciting journey, but before you start touring properties, it’s essential to get pre-approved for a mortgage. A Mortgage Pre-Approval Checklist helps you understand how much you can borrow and shows sellers that you’re a serious buyer. It can also speed up the home-buying process and give you a competitive edge in a busy real estate market.
This mortgage pre-approval checklist outlines everything you need before house hunting, from financial documents to credit preparation, so you can approach lenders with confidence.
What Is Mortgage Pre-Approval?
Mortgage pre-approval is a process where a lender reviews your financial information to determine how much money they’re willing to lend you. Unlike pre-qualification, pre-approval involves a more detailed review of your income, credit history, assets, and debts.
Once approved, you’ll receive a pre-approval letter that states the maximum loan amount you qualify for. Most pre-approval letters are valid for 60 to 90 days.
Why Is Mortgage Pre-Approval Important?
Getting pre-approved before house hunting offers several advantages:
- Helps determine your home-buying budget
- Makes your offer more attractive to sellers
- Speeds up the mortgage approval process
- Identifies potential financial issues early
- Gives you confidence while searching for a home
Many sellers prefer buyers who already have mortgage pre-approval because it reduces the risk of financing delays.
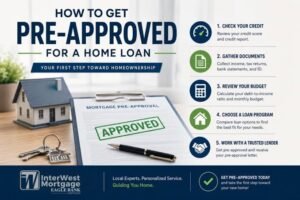
Check Your Credit Score
Your credit score is one of the first things lenders evaluate. A higher score can improve your chances of approval and help you qualify for lower interest rates.
Before applying:
- Review your credit report
- Dispute any errors
- Pay bills on time
- Reduce outstanding debt
- Avoid opening new credit accounts
Improving your credit score before applying can save you money over the life of your mortgage.
Gather Your Income Documents
Lenders need proof that you have a stable income and can repay the loan.
Prepare these documents:
- Recent pay stubs
- W-2 forms
- Tax returns from the past two years
- Bonus or commission statements (if applicable)
- Social Security or pension income documentation
- Self-employment income records, if applicable
Having these documents ready helps avoid delays during the approval process.
Collect Bank Statements
Your lender will review your financial assets to verify your ability to cover the down payment, closing costs, and reserve funds.
Gather:
- Checking account statements
- Savings account statements
- Investment account statements
- Retirement account statements
- Certificates of deposit (CDs)
Large or unusual deposits may require additional documentation, so be prepared to explain them.
Verify Employment
Stable employment reassures lenders that you have reliable income.
You may need:
- Employer contact information
- Employment verification letter
- Recent pay history
- Self-employment documentation, if applicable
Avoid changing jobs during the mortgage approval process unless absolutely necessary.
Calculate Your Debt-to-Income Ratio
Your debt-to-income (DTI) ratio compares your monthly debt payments to your gross monthly income.
Monthly debts include:
- Credit card payments
- Auto loans
- Student loans
- Personal loans
- Existing mortgage payments
- Child support or alimony
Lowering your DTI ratio before applying can improve your chances of approval.
Prepare Your Down Payment
Although some mortgage programs allow low down payments, having more savings can strengthen your application.
In addition to the down payment, plan for:
- Closing costs
- Home inspection fees
- Moving expenses
- Homeowners insurance
- Emergency savings
Being financially prepared helps reduce stress after purchasing your home.
Gather Personal Identification
Lenders typically require identity verification.
Keep these documents available:
- Government-issued photo ID
- Social Security number
- Permanent resident documentation (if applicable)
- Proof of address
Providing accurate information helps prevent unnecessary delays.
Avoid Financial Changes Before Approval
Once you’ve started the pre-approval process, maintain financial stability.
Avoid:
- Applying for new credit cards
- Financing a vehicle
- Making expensive purchases
- Missing loan or credit card payments
- Closing existing credit accounts
Even small financial changes can affect your mortgage approval.
Compare Multiple Mortgage Lenders
Don’t accept the first mortgage offer you receive. Shopping around may help you secure better terms.
Compare lenders based on:
- Interest rates
- Annual Percentage Rate (APR)
- Loan programs
- Closing costs
- Customer service
- Processing times
Choosing the right lender can save thousands of dollars over the life of your loan.
Questions to Ask Your Lender
Before moving forward, ask your lender:
- What loan programs do I qualify for?
- What is my maximum loan amount?
- What interest rate can I expect?
- What will my estimated monthly payment be?
- How long will the approval process take?
- What are the estimated closing costs?
Having clear answers helps you make informed financial decisions.
Mortgage Pre-Approval Checklist
Use this checklist before applying:
- Check your credit score
- Review your credit report
- Gather pay stubs
- Collect tax returns
- Prepare bank statements
- Verify employment
- Calculate your debt-to-income ratio
- Save for your down payment
- Gather identification documents
- Compare mortgage lenders
- Avoid new debt
- Prepare questions for your lender
Completing these steps will help ensure a smoother and faster mortgage approval process.
Final Thoughts
Getting pre-approved for a mortgage is one of the smartest steps you can take before house hunting. It gives you a clear budget, strengthens your buying position, and helps you avoid surprises during the home-buying process. By organizing your financial documents, improving your credit, reducing debt, and comparing lenders, you’ll be well-prepared to secure the financing you need.
With this mortgage pre-approval checklist in hand, you can begin your search for the perfect home with confidence and peace of mind.